For the right buyer, yes. Rates are still high, but they've come down three weeks in a row. Buyers have more homes to choose from and more room to negotiate than they've had in years. And waiting for a better moment usually costs more than it saves.
That said, "the right buyer" matters. Buying before you're ready is its own mistake. Let me walk you through what's actually happening in Sammamish right now, what it means for your payment, and how to use the current market without irritating the sellers you're hoping to buy from.
The Short Answer
If you have stable income, a down payment, and a cushion beyond it, this is a market worth stepping into. You have time to compare. You have options. You have more room to bargain than in the last few years.
If your income is uncertain, you're not sure you'll stay in the area, or you haven't saved enough beyond the down payment, wait. I've told buyers that for 35 years, and I'll tell you the same.
Here's how I'd think it through.
What Rates Are Actually Doing
Let's start with the number everyone asks about.
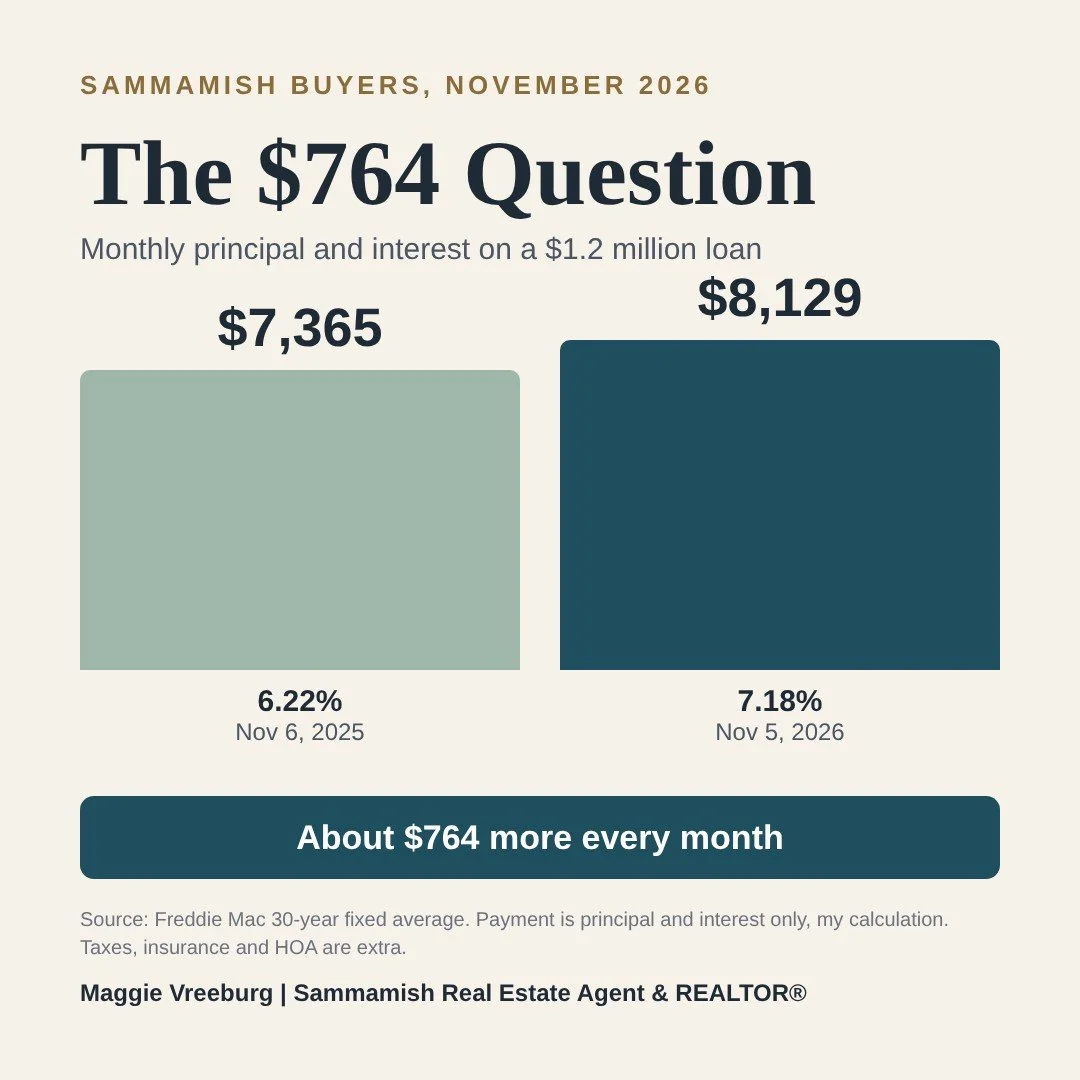
Freddie Mac reported the average 30-year fixed rate at 7.18 percent on November 5, 2026. That was the third weekly decline in a row. A year earlier, on November 6, 2025, it was 6.22 percent.
That's almost a full point higher than last year. On a $1.2 million loan, here's what it does:
At 6.22 percent, principal and interest runs about $7,365 a month.
At 7.18 percent, it runs about $8,129 a month.
The difference is about $764 a month.
That's my own math on a standard 30-year loan. It leaves out taxes, insurance, and HOA fees. Jumbo loans can price a little differently, so get a quote from a local lender who knows the Eastside.
I won't pretend $764 a month is small. It's real money. But here's what I've seen over 35 years: rates move, and buyers who wait for the perfect number often miss the homes they wanted. "For a full breakdown of what buying in Sammamish costs, including taxes, HOA fees, and closing costs, I've covered that separately." → https://www.maggievreeburghomes.com/blogs/how-much-does-it-cost-to-buy-a-home-in-sammamish-wa
Waiting for Lower Rates Isn't Foolish. It's Just Not Free.
I understand the instinct. If rates drop, your payment drops.
But when rates fall, more buyers come back. More buyers means more competition. More competition means firmer prices, fewer concessions, and multiple offers on the homes you like. You'd be trading the room you have today for a rate nobody can promise.
You can change your rate later. If rates fall meaningfully, refinancing may be an option. It costs money and it's never guaranteed, so I never tell buyers to count on it. But you can't go back and change the price you paid or the home you lost to another buyer.
I've watched this happen. Sellers who waited for a better time watched their home values drop $100,000. Buyers who waited for a better rate often found that when it came, so did everyone else.
What the Sammamish Market Looks Like Right Now
I want to be careful with numbers here. I don't have fresh MLS data in this article, so I'm using Zillow's figures for Sammamish through the end of August 2026. Ask me for the latest on any street or neighborhood you're considering.
Zillow showed:
A typical Sammamish home value of about $1.52 million, down roughly 5 percent from a year earlier.
About 68 percent of sales closing under list price, and about 16 percent over.
A median sale-to-list ratio of 0.982. On a $1.5 million home, that's roughly $27,000 under list.
A median of 44 days to go pending.
About 347 homes for sale.
That tells me three things. Buyers have choices. Homes aren't flying off the market in a weekend. And the typical sale closes a little under list, not a lot.
Notice what that doesn't say. It doesn't say every home is a bargain. The homes that sell near or over list are the ones that are priced right and show well. The ones that sit are the ones that aren't. Same market, very different outcomes.
The Real Advantages of Buying Now
More choice. When inventory is thin, you take what you can get. Right now you can compare neighborhoods, floor plans, and lots. You can say no to a home that's almost right.
Time to think. You don't have to submit an offer in 24 hours without seeing the home twice. Take your time. Just don't mistake having time for having forever.
Room to negotiate. More on this below. It exists, but it has to be used with respect.
Less pressure from other buyers. Fewer multiple-offer situations on well-priced homes means you can make a thoughtful decision.
Winter buyers get taken seriously. Sellers who list in November and December usually have a reason to sell. They respond to serious, well-prepared buyers.
A rate you can revisit. Not a promise, but an option. A price you can't revisit. "If you're weighing renting against buying, I've written that out separately." → https://www.maggievreeburghomes.com/blogs/should-i-rent-or-buy-in-sammamish-right-now-the-honest-answer
How to Negotiate Without Irritating the Seller
This is where I get protective of both sides. I represent buyers, and I also live in this community. Sellers here are people. Many raised their kids in these homes. An insulting offer doesn't just get rejected. It can sour the whole negotiation.
Here's how I approach it:
Start with the comparable sales, not the list price. If the home is priced right, a fair offer close to list is respectful and often accepted. If it's priced high, comps give you a calm, factual reason to offer less.
Skip the lowball. A bottom-of-the-barrel offer usually gets ignored. It also tells the seller you're not serious.
Ask for what matters. A closing cost credit, a rate buydown, a repair, or a flexible closing date can be worth more than a small price cut. Ask your lender what a buydown costs before you ask for one.
Be flexible on timing. Some sellers need a quick close. Others need extra time. Flexibility is often more valuable to them than a few thousand dollars.
Send a strong, clean offer. Pre-approval letter, reasonable terms, no drama. In my experience, the best offer isn't always the highest one. It's the one the seller feels good about.
Keep your inspection. Washington is a buyer-beware state. Your inspection is one of your most important protections, and there are better ways to be competitive than giving it up.
Be respectful in every message. Sellers talk to their agents about who they want to work with.
Negotiating well isn't about winning. It's about getting a fair deal and a smooth close, with both sides walking away feeling good about it. "For the full step-by-step process from pre-approval to closing, I've covered that separately." → https://www.maggievreeburghomes.com/blogs/what-is-the-home-buying-process-like-in-sammamish-wa
Who This Market Is Built For
I'd tell you to take a serious look if:
You have stable income and a clear sense of what you can afford.
You're renting and your payment isn't building anything.
You're relocating to the Eastside for work and need to settle quickly.
You have kids and want to be in the right school boundary before the next school year.
You've been outbid before and want a calmer market to try again.
If that sounds like you, waiting isn't a strategy. It's a cost.
Who Should Wait
Honesty matters here, too.
I once worked with first-time buyers who were eager to buy but simply hadn't saved enough. The loans they could qualify for would have meant private mortgage insurance and a payment that stretched them. I advised patience. We stayed in touch for a year. They saved more, researched loans, and looked at buyer bonus programs. When we went back out, we found them a home and negotiated it in a single weekend. They bought with 20 percent down, no PMI, and at a lower price than a year before.
Waiting worked for them because they used the time. They didn't wait for the market. They waited to be ready.
Wait if your income isn't stable, if you're unsure how long you'll stay, or if you don't have a cushion beyond your down payment. The right home at the wrong time is still the wrong decision. "If you're buying your first home, I've written about what to know before you start." → https://www.maggievreeburghomes.com/blogs/is-sammamish-good-for-first-time-homebuyers-the-honest-answer
A Relocating Buyer's Example
I worked with a family, the Barleys, who relocated from out of state with two kids and specific school needs. We chose neighborhoods online before they arrived and coordinated school visits ahead of time. They knew exactly what they could afford and why.
When the right home came up, they were ready. They won against multiple competing offers. Not because they overpaid, but because they weren't scrambling to figure out financing at the last minute.
That's the advantage of being prepared. It matters even more in a market where good homes still sell quickly. "For everything else a relocating family needs to know, I've put it all in one place." → https://www.maggievreeburghomes.com/blogs/moving-to-sammamish-wa-your-complete-relocation-guide
Common Mistakes Buyers Make Right Now
Waiting for rates to hit a specific number. Nobody can time it. Get pre-approved and know your real payment.
Treating "more inventory" as "everything is a deal." Well-priced, well-prepared homes still draw offers.
Making an offer that disrespects the seller. Fair and factual wins more often than aggressive.
Skipping the jumbo loan conversation. Most Sammamish purchases are above conforming limits. Start that talk early.
Looking only at the monthly payment. Taxes, HOA, insurance, and maintenance are part of the real number.
Waiving the inspection to look strong. It's a protection you want to keep.
Falling for a home with a problem you can see and ignoring one you can't. Smell, water, and deferred maintenance tell you a lot.
What I'd Tell a Family Member
Get pre-approved. Know your real monthly number. Pick two or three neighborhoods that fit your life. Take your time, but not forever.
Then make a fair, strong offer on the right home. Don't try to win by squeezing a seller. Try to win by being the buyer they feel good about.
Frequently Asked Questions
Is now a good time to buy a home in Sammamish? For buyers with stable income, a down payment, and a financial cushion, yes. There is more choice and more room to negotiate than in recent years. Rates are still high, though, so know your real monthly payment before you start.
What are mortgage rates right now? Freddie Mac reported the average 30-year fixed rate at 7.18 percent on November 5, 2026, the third weekly decline in a row. A year earlier it was 6.22 percent. Jumbo loans can price differently, so get a quote from a local lender.
Can I negotiate on a Sammamish home right now? Often, yes. Zillow's data through August showed the typical Sammamish home sold about 2 percent under list price. But well-priced, well-prepared homes still draw strong offers. Negotiate with comparable sales and reasonable requests, not lowballs.
Should I wait for rates to drop before buying? Nobody can predict rates. If they drop, more buyers return, and that can mean more competition and firmer prices. You can refinance later if rates fall meaningfully, though that is never guaranteed. You can't change the price you pay.
How much do I need to buy in Sammamish? It depends on the price, your down payment, and your loan. On a $1.2 million loan at 7.18 percent, principal and interest is about $8,129 a month before taxes, insurance, and HOA fees. A local lender can give you an exact number.
Ready to Run the Real Numbers?
If you're thinking about buying in Sammamish and want honest guidance about timing, pricing, and negotiation, Maggie Vreeburg can help you understand your options.
Dig with the right questions, stop talking, and actually listen to what a buyer is worried about. That's when the right plan takes shape. That's when I come in.
Maggie Vreeburg | Sammamish Real Estate Agent & REALTOR® maggievreeburghomes.com 425-417-4663 Hello@MaggieVreeburgHomes.com
